We keep abreast of local and global trends to assess their potential impact on our markets and customers. We review our strategy to capture new opportunities and mitigate emerging risks created by changes in our operating context.
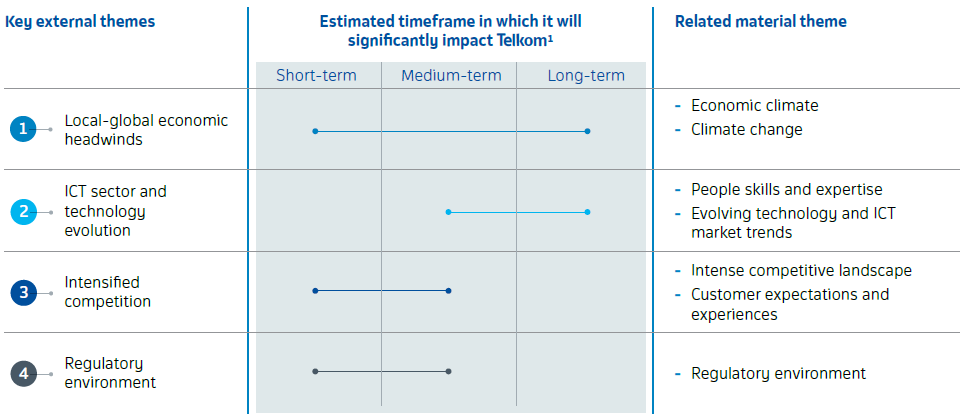
| 1 | For this report, short term is the next financial year (ending 31 March 2023), medium term is the period to 31 March 2025 and long term is beyond April 2025. |
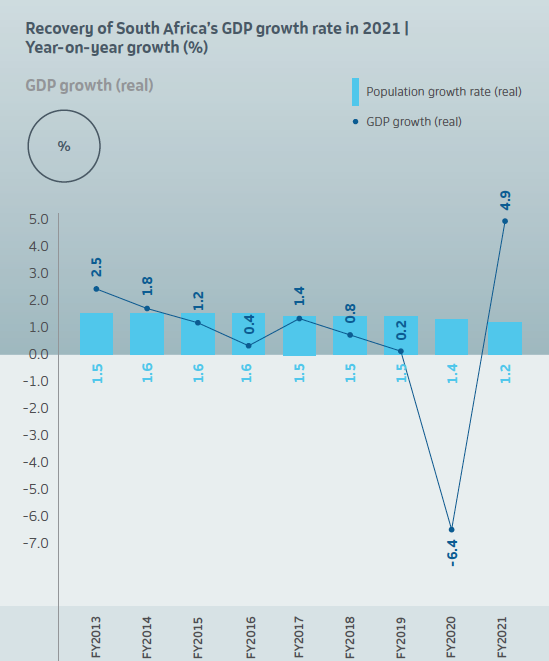
South Africa had a strong economic recovery from the ongoing COVID-19 pandemic, despite the unrest, cyberattacks and strikes during July 2021. Real gross domestic product (GDP) growth increased to 4.9% in 2021, following the large decline of 6.4% in 2020. GDP is expected to grow by 1.7% in 2022. This slowdown in growth is due to a fading rebound from the COVID-19 pandemic, alongside stagnant global economic growth due to the conflict in Eastern Europe and rising global inflation. Real GDP is expected to grow by 1.8% in 2023, but this may be impacted by extreme weather conditions (e.g. severe droughts or high-intensity tropical cyclones) linked to climate change.
We consider the risk of higher borrowing and input costs due to higher inflation and high commodity prices. We focus on sustainable cost management and targeted capital investments to mitigate the downside risk of lower economic growth and climate change considerations. Risks associated with climate change are integrated into Telkom's risk identification, management and assurance processes.
Further reading
It is expected that remote working practices will continue to support hybrid work from home/office policies in FY2023 and beyond. Despite some return of face-to-face interactions, there is still demand for good quality, high-speed broadband services that enable streaming and video-heavy collaboration tools.
Customers still demand fibre and mobile services that can adapt flexibly to their requirements. New business models are emerging as the role of service providers evolves beyond network security to end-to-end security. The growth in cloud services (41% growth in 2021) leads to a decline in traditional on-premises enterprise technology products and services. As a result, integrated cloud/SD-WAN solutions are becoming increasingly important enablers for integrated security, home broadband and office applications. This increases the demand for people with skills in emerging technologies such as cloud, data analytics, automation and AI.
Telkom ensures that the end-to-end communications network (access, aggregation and transmission) is constantly available and can scale appropriately in line with increased subscribers and exponential traffic growth.
We develop integrated solutions for selected vertical markets, including health and retail. These combine connectivity and information security with tailored ICT applications to expand South Africa's digital footprint. There are opportunities to use aggregation nodes and new network topologies to bring data centres and cloud-based computing power closer to the edge.
We seek an optimal balance between crafting meaningful partnerships and developing internal skills and capabilities to meet customer expectations. Over the past year we have hired additional data analysts, AI specialists, cloud architects and cybersecurity experts to boost our capabilities in these areas.
Further reading
Social and relationship capital

The South African ICT sector remains highly competitive, with an increasing focus on customer experience. The increasing demand for communications, particularly data services, resulted in price reductions across major network providers (fixed and mobile). The ongoing state of emergency resulted in customers seeking cost-effective connectivity to live, work and play at home. As fixed and mobile network operators invest heavily in network infrastructure, capacity and coverage are enhanced. They seek ways to monetise their investments through competitive and disruptive pricing.
We expect competition from the two leading mobile operators to increase further, following the release of additional spectrum in the March 2022 spectrum auction.
Telkom's data-led strategy remains the central focus and we maintain a value-led pricing strategy across all product portfolios. The continued investment in fixed and mobile network technologies aims to provide customers with quality network experiences at affordable prices. Many of Telkom's segmented customer value propositions have been replicated by competitors, enforcing the notion that Telkom continues to lead the data market.
As data becomes more affordable and pricing parity is reached, differentiation through value-added services and non- connectivity revenue remains critical. We are working tirelessly to offer customers true fixed and mobile convergence to expand our integrated product offerings. We are pleased to note that our efforts to improve customer experience are bearing fruit, with Telkom recording the largest year-on-year improvements in reputational and operational net sentiment relative to the other local wireless network providers (2021 South African Telecommunications Sentiment Index, Deloitte).
Further reading
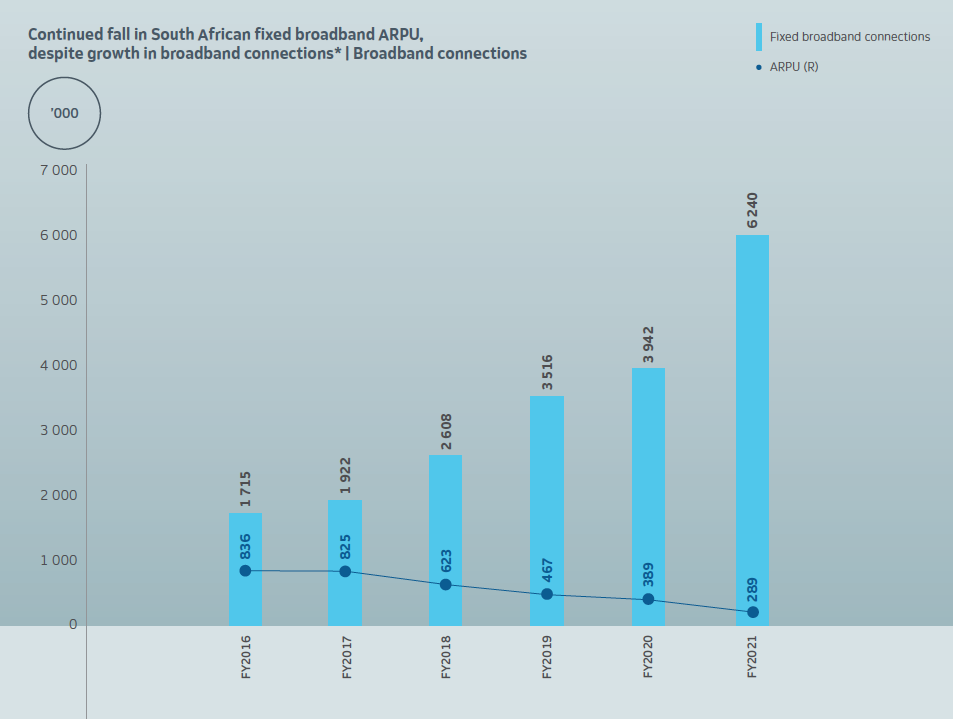
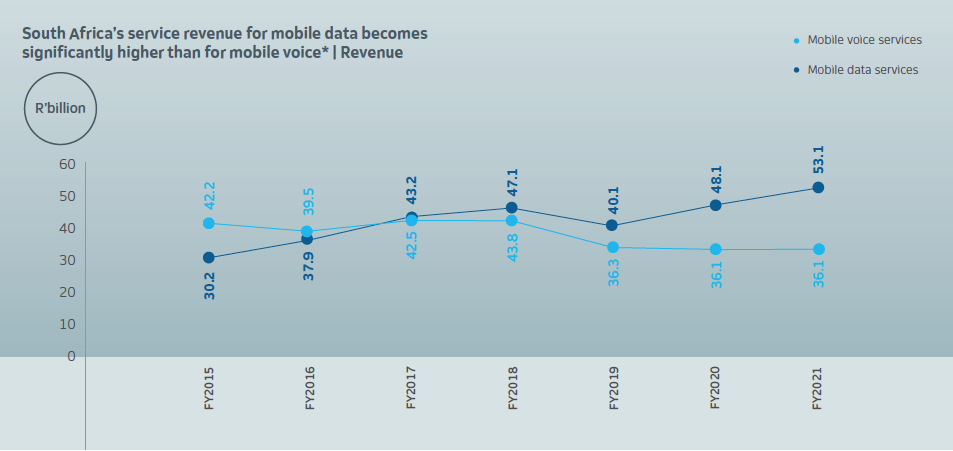
The release and licensing of additional high-demand spectrum are key to determining the future structure of South Africa's mobile communications market as it continues the transition from mobile voice to mobile data services (see adjoining chart). After following a legal process to ensure that the high-demand spectrum is licensed pro-competitively, Telkom reached an out-of-court settlement with ICASA on 8 April 2022. In terms of the settlement, ICASA has undertaken to auction the unsold 800 MHz lot and any other spectrum that is presently available for licensing (except for the spectrum set aside for the WOAN) before the end of the current financial year. Here it will consider the spectrum holdings emanating from the recently concluded auction, including the imbalances in the sub 1 GHz bands and the impact of the outcome of the auction on competition in the mobile market. Furthermore, ICASA has undertaken to conduct an inquiry into the existence of a secondary market for spectrum. This will include assessing whether there is a need for regulatory intervention.
ICASA published the mobile broadband services regulations and reasons document on 31 March 2022. These regulations serve to monitor the activities of our competitors in the markets in which they have found to have significant market power, namely the markets for mobile retail services, wholesale site infrastructure access (including access to DAS) and national roaming. Telkom trusts that the regulations will assist in achieving a more level playing field where it can compete more equitably.
ICASA's current call termination review will determine the call termination rates for the next three years. Telkom hopes that the new glide path will assist in supporting pro-competitive outcomes in the voice market.
Telkom remains steadfast in its belief that enabling competition in the electronic communications sector is paramount for the health of the sector and the economy at large. To achieve this, the licensing process of spectrum needs to be carried out in a responsible and pro-competitive manner. We remain cooperative in seeking a solution that ensures the future process of assigning high-demand spectrum will result in a market structure that supports fair and effective competition with the larger mobile operators. Similarly, Telkom is supportive of a pro-competitive approach to the mobile broadband services inquiry and call termination rate review.
Telkom trusts that the call termination review will prove that retaining the current approach to mobile termination asymmetry is pro-competitive and that the reintroduction of regulated international termination rates will assist with curbing by-pass fraud.
Further reading
Engaging with our stakeholders
Enterprise risk management Enterprise risk management and compliance